

Blogs
PW Consulting: White Fused Alumina Market Hits $200M in 2025, Projects 4.01% CAGR Through 2032
By PW Consulting, 2026-09-16
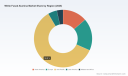
White Fused Alumina Market 2026: Strategic Intelligence for Industrial Decision-Makers
As industrial manufacturing enters a new cycle of material optimization and cost discipline, White Fused Alumina has emerged as a critical component across abrasives, refractories, and technical ceramics. The global market has demonstrated consistent expansion over the past five years, growing from 150.0 Million USD in 2020 to 200.0 Million USD in 2025, with revenue projections indicating a continued upward trajectory through the end of the decade. Our latest White Fused Alumina Market research is built to translate this trajectory into executable strategy, giving procurement leaders, product developers, and market planners a precise, evidence-based view of where value is being created and where competitive pressure is intensifying.
This analysis is not a static snapshot. It is a forward-looking strategic instrument calibrated for the 2026 decision window. By combining historical performance from 2020 through 2025 with a structured forecast spanning 2026 to 2032, the report enables stakeholders to test assumptions, align supply commitments, and prepare for shifting demand patterns without relying on fragmented secondary sources or outdated industry narratives.
Market Trajectory and the Strategic Meaning of the Growth Curve
The market's evolution reflects more than incremental volume growth. The progression from 159.67 Million USD in 2021 to 170.69 Million USD in 2022, followed by acceleration toward 185.97 Million USD in 2023 and a measured 187.12 Million USD in 2024, shows a sector that has absorbed supply disruptions, raw material volatility, and regional demand rebalancing while still advancing ahead of broader industrial benchmarks. The 200.0 Million USD baseline in 2025 reinforces a market that has stabilized around quality differentiation, application-specific grading, and more disciplined inventory management.
From a strategic planning perspective, the forecast period tells its own story. Revenue is expected to reach 215.16 Million USD in 2026, followed by 217.06 Million USD in 2027 and 229.1 Million USD in 2028. The projection continues into 2029 at 231.99 Million USD, approaches 248.89 Million USD by 2030, and then moves toward 245.29 Million USD in 2031 before reaching 263.29 Million USD in 2032. These are not arbitrary numbers. They are planning inputs that help organizations gauge capacity timing, contracting windows, and the pace at which high-performance grades may capture additional share as downstream users demand better wear resistance, thermal stability, and polished surface outcomes.
The overall growth profile supports a compound annual growth rate of 4.01 percent across the forecast horizon, indicating a market that rewards companies able to align product specifications with end-use performance requirements rather than competing solely on commoditized volume. For 2026 planning, this means the strategic question is less about whether demand will advance and more about how to position specifications, supply agreements, and regional sourcing decisions to capture margin in a market where performance credibility increasingly determines customer retention.
Report Architecture: What Decision-Makers Will Find Inside
The study is organized to convert market complexity into operational clarity. Rather than offering a high-level overview alone, the report maps the market across type, application, and regional demand structures so that readers can align internal assumptions with external evidence. The segmentation logic is designed for practical use: it helps teams understand where white fused alumina is being specified, which grade structures are gaining emphasis, and how application requirements are reshaping procurement priorities.
Fused Magnesia Market
Inside the report, stakeholders will find:
- A full market size reconstruction from 2020 through 2025, providing a verifiable historical baseline for internal forecasting and board-level review.
- A detailed 2026 to 2032 outlook that translates growth momentum into planning-relevant signals for capacity, sourcing, and product roadmap decisions.
- Type-level analysis that distinguishes among refractory, abrasive, and ceramic-grade demand patterns, supporting product positioning and specification strategy.
- Application-level evaluation that examines how refractories, abrasives, and ceramics usage shapes volume flows and customer requirements.
- Regional demand mapping that reveals where consumption is concentrated and how geographic dynamics influence pricing, logistics, and sourcing strategy.
- Competitive profile coverage of the leading producers, including operational focus, product offerings, and strategic positioning within the white fused alumina value chain.
- Synthesis of industry dynamics that connects supply-side realities with downstream performance expectations, giving readers context for scenario planning and risk assessment.
The report is intended for teams that need more than directional commentary. It provides a structured foundation for budgeting, segment prioritization, customer strategy, and competitive positioning in a market where small specification advantages can translate into long-term contract value.
Competitive Landscape: Who Shapes the Market and How
The white fused alumina market is defined by a mix of established industrial suppliers and regionally influential producers, each bringing a different balance of purity, scale, application focus, and geographic reach. Our analysis examines the companies that materially influence pricing behavior, grade availability, and supply reliability, allowing readers to benchmark their own positioning against the actors most likely to affect purchasing decisions in 2026 and beyond.
Washington Mills operates with a clear emphasis on high-purity output, manufacturing white fused alumina grains, powders, and bubbles via electric arc fusion of Bayer-processed alumina. With material purity exceeding 99 percent Al2O3, the company supports demanding uses in refractories, ceramics, abrasives, and polishing applications. For customers where consistency and purity are non-negotiable, this profile signals a supplier orientation toward performance-sensitive segments rather than volume-only competition.
Imerys brings a broad, globally distributed production footprint to the market. With 12 global production sites, the company produces fused alumina, including white fused alumina, under the Alodur brand for abrasives, refractories, and technical ceramics. That scale and brand architecture matter in procurement environments where supply continuity, multi-region coverage, and application versatility are weighed alongside price.
Rusal contributes to the landscape through large-scale electric arc furnace production of white fused alumina from pure alumina at its Boksitogorsk Alumina Refinery. The company's integration with upstream alumina resources gives it a distinct supply-chain posture, which can influence cost structure, volume reliability, and the ability to serve industrial users seeking stable baseline supply.
U.S. Electrofused Minerals positions white fused alumina within a broader fused oxides portfolio for industrial applications. Its approach reflects a practical, application-oriented supply model in which white fused alumina is part of a wider materials offering, allowing customers to consolidate sourcing across related oxide products where specification alignment is possible.
MOTIM Electrocorundum provides another important European reference point, producing high-quality white fused alumina for refractories and abrasives. Its specialization reinforces the market's split between performance-driven and cost-sensitive purchasing channels, as well as the continued relevance of regional manufacturers that combine technical consistency with proximity to key industrial users.
In the Asia-Pacific supply structure, Zhengzhou Yufa Group stands out as a large-scale producer with a strong emphasis on cost-efficient supply for global abrasives and refractories. Henan Ruishi Renewable Resources Group similarly supplies white fused alumina grains and powders for industrial use, adding to the region's manufacturing depth and reinforcing the competitive importance of volume capability, logistics efficiency, and pricing agility.
Together, these players illustrate a market where concentration creates both opportunity and caution. The sector's structure indicates that a limited number of producers account for a substantial share of revenue, while still leaving room for specialized suppliers to compete on grade, purity, and service. For 2026 strategy, that means competitive intelligence cannot stop at product specs; it must also address supplier reliability, regional coverage, and the ability to respond to application-specific demand shifts.
Industry Context and Strategic Implications for 2026
The market intelligence in this study is grounded in current industrial realities. White fused alumina demand does not evolve in isolation. It is shaped by how abrasives manufacturers balance surface-finishing performance against cost, how refractory producers evaluate thermal endurance and service life, and how ceramics users align material characteristics with component requirements. At the same time, supply-side considerations such as energy intensity, raw alumina availability, furnace operation efficiency, and logistics constraints influence how reliably producers can meet specification-sensitive orders.
For 2026 planning, these dynamics create several strategic priorities. Companies need to evaluate whether their product and sourcing strategies are aligned with the growing importance of high-consistency grades. Procurement teams must weigh whether multi-supplier structures or consolidated partnerships better serve their risk and performance requirements. Market leaders need to determine where differentiation is sustainable, particularly in applications where wear life, polish quality, and thermal behavior directly affect downstream economics.
The report also supports scenario-based thinking. Because the forecast extends through 2032, organizations can use it to test how changes in regional demand strength, application mix, or grade adoption might alter revenue potential and competitive intensity. That forward visibility is especially valuable for capital planning, long-term contracts, and product development roadmaps where premature commitments can erode flexibility and delayed moves can cede share to more responsive competitors.
White Fused Alumina Market
Why This Research Matters Now
The white fused alumina market is entering a phase where informed decisions will separate resilient operators from those forced to react to supply and pricing shifts after the fact. With a 2025 baseline of 200.0 Million USD and a forecast that points toward 263.29 Million USD by 2032, the market offers meaningful expansion, but it also demands sharper segmentation insight, supplier benchmarking, and application-level understanding. Organizations that enter 2026 with only generic market narratives will be at a disadvantage when negotiating with producers, specifying grades for sensitive applications, or deciding where to invest in capability and coverage.
This White Fused Alumina Market research is designed to close that gap. It translates verified historical data, forward projections, and competitive profiling into a usable strategic framework for 2026 decision-making. The full intelligence set, including deeper segmentation detail, regional demand analysis, and complete company profiles, is available through the complete report. For teams that need precise market estimates, actionable segmentation, and a clear view of who is shaping the competitive environment, the full study provides the depth required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laboratory Animal Housing Cage Market to Reach $307.5M in 2025, Grow at 4.45% CAGR
By PW Consulting, 2026-09-16
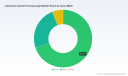
Strategic Intelligence for Decision-Makers: The Global Laboratory Animal Housing Cage Market in 2026
The laboratory animal housing cage market sits at the intersection of biopharma innovation, regulatory evolution, and operational efficiency. For executives, procurement leaders, and R&D strategists, understanding the trajectory of this specialized infrastructure market is not merely an operational concern—it is a strategic imperative. Our latest comprehensive market research on the Laboratory Animal Housing Cage Market provides a rigorous, data-driven foundation for 2026 decision-making, mapping historical performance, forecasting growth through 2032, and dissecting the competitive, regulatory, and technological forces that will shape procurement strategies, facility investments, and partnership opportunities in the coming years.
This article serves as a strategic preview of the full study. It outlines the analytical architecture, highlights the macro market trajectory, contextualizes the regulatory and competitive landscape, and demonstrates how the complete report translates complex intelligence into actionable frameworks for enterprise planning.
Market Trajectory: From Baseline to Forecast Horizon
The market has demonstrated resilient, structurally supported growth over the historical reference period, reflecting sustained demand from research institutions, contract research organizations, and pharmaceutical developers. Our analysis establishes a clear baseline trajectory, with market revenue climbing from approximately 247.8 million USD in 2020 to 307.5 million USD in 2025. This progression underscores a market that has absorbed operational disruptions, adapted to evolving husbandry standards, and continued to expand in line with broader life sciences investment cycles.
Looking ahead, the forecast window from 2026 through 2032 projects continued expansion, with an estimated CAGR of 4.45 percent. The forward curve suggests that demand will be driven by a combination of facility modernization, heightened emphasis on animal welfare and reproducibility, and the gradual uptake of advanced housing architectures across regions and research applications. By 2032, the market is positioned to cross 400 million USD in annual revenue, a threshold that signals both mature adoption in established markets and meaningful growth momentum in emerging research ecosystems.
Importantly, this trajectory is not uniform. The interplay of regional research intensity, species-specific housing requirements, and material-technology preferences introduces structural variation across market segments. The complete report quantifies these variations with disciplined granularity, allowing decision-makers to align procurement roadmaps and capital allocation with the most relevant demand vectors for their operational footprint.
Report Architecture: From Macro Trends to Operational Playbooks
The full study is designed to function as a decision-support instrument rather than a static data repository. Its architecture moves from macro market structure to segment-level dynamics, then to competitive positioning, regulatory mapping, and forward-looking scenario analysis. Each section is anchored by customizable modeling inputs, enabling clients to stress-test assumptions against their own facility portfolios, geographic exposure, and research pipelines.
Key analytical components of the report include:
- Macro market sizing and forecast modeling across the 2020–2032 horizon, with explicit base-year calibration and scenario sensitivity around adoption velocity and capital expenditure cycles.
- Segment-level demand mapping that distinguishes between housing material architectures, species and application categories, and regional research infrastructure profiles, allowing organizations to isolate the demand pools most relevant to their product or service strategy.
- Competitive landscape assessment covering ten leading suppliers, with company profiles, product-system specializations, and a timeline of recent commercial and strategic moves that signal where the market is heading.
- Regulatory and compliance mapping that translates directives, accreditation requirements, and institutional guidance into operational implications for cage design, ventilation standards, sanitation schedules, and environmental control.
- Inventory of industry dynamics and ecosystem signals, including trade engagement, educational program expansion, partnership activity, and product-introduction cadence, that together reveal the cadence of innovation and market entry.
By structuring the analysis in this way, the report enables executives to answer practical questions: where is demand most concentrated, which housing platforms are gaining traction, how do compliance requirements translate into procurement specifications, and which supplier capabilities are becoming differentiators rather than table stakes.
Regulatory Dynamics as a Demand Catalyst
Regulatory and accreditation frameworks are not peripheral constraints; they are structural drivers of housing specification, replacement cycles, and facility upgrade spending. Across major research jurisdictions, animal welfare standards, environmental control expectations, and reproducibility mandates are progressively tightening, compelling institutions and service providers to align infrastructure with documented compliance requirements.
The complete report synthesizes multiple layers of regulatory context into an actionable dynamics section. This includes how requirements for environmental enrichment, temperature stability, humidity control, and minimum cage dimensions influence housing system design and procurement specifications. It also addresses how accreditation frameworks and institutional oversight create consistent demand for certified housing solutions that support animal welfare, biosecurity, and research reproducibility. Furthermore, the analysis maps sanitation frequency expectations and microenvironmental monitoring protocols, showing how modern individually ventilated cage architectures can align with operational efficiency targets while maintaining compliance.
For strategic planners, the regulatory dimension is best understood as a forcing function. As institutions seek to harmonize welfare standards with throughput goals and environmental control precision, investment flows toward housing systems that integrate ventilation performance, sanitation durability, and compatibility with monitoring or tracking technologies. The report quantifies the magnitude of these influences and maps them to realistic procurement and capital planning horizons.
Competitive Landscape: Ten Anchors and a Shifting Innovation Frontier
The market is characterized by meaningful concentration among established suppliers, with a closely contested field of specialized manufacturers competing on system architecture, durability, compliance alignment, and digital integration. The report profiles ten core companies, each with distinct positioning across plastic and metal housing platforms, individually ventilated cage systems, large-animal housing solutions, and specialty accessories or environmental control equipment.
Laboratory Animal Housing Cage Market
Several competitive themes emerge from the profile set. First, a growing emphasis on modular, reusable, and high-density housing platforms reflects the pressure to optimize facility space while maintaining throughput and welfare standards. Second, the integration of RFID census compatibility, ergonomic handling features, and digital ventilation control points toward an operational shift from static housing to data-enabled environment management. Third, durability claims around repeated autoclave cycling and multi-species versatility are becoming material evaluation criteria for procurement teams weighing lifecycle cost against upfront specification.
The full report situates these profiles within a structured competitive analysis, including concentration metrics that illustrate the degree of market consolidation and the strategic implications for sourcing strategy, supplier diversification, and partnership development. Rather than presenting company information in isolation, the study maps competitive capabilities against the demand segments they serve, helping clients identify where incumbents hold structural advantages and where whitespace may exist for differentiated offerings or specialized contracting models.
Worldwide Animal Workstation Market
Recent Commercial and Strategic Signals
Competitive dynamics are not static; they are continuously reshaped by trade engagement, partnership formation, product introductions, and educational outreach. The report captures a curated set of recent developments that reveal how leading suppliers are positioning themselves for the next phase of market growth.
Several patterns stand out in the recent activity set. Trade-show participation and conference presence continue to function as core visibility channels, with leading firms showcasing next-generation housing systems, ventilation platforms, and husbandry-integrated equipment to research and facility audiences. At the same time, educational programming is increasingly used not only for brand visibility but also to deepen engagement around husbandry best practices and housing equipment integration, reinforcing long-term relationships with research communities.
On the product and partnership side, recent moves indicate a strategic pivot toward AI-enabled monitoring integrations, ergonomic and reusable housing designs, and RFID-compatible census systems. These developments suggest that suppliers are responding to facility-level pressures around space utilization, operational consistency, and data-driven animal management. For procurement and R&D leaders, the signal is clear: housing decisions are increasingly inseparable from broader facility technology strategies.
The complete report integrates these developments into a timeline and competitive-context framework, allowing clients to interpret commercial activity not as isolated announcements but as indicators of strategic direction, capability investment, and likely future specification trends.
Implications for 2026 Enterprise Decision-Making
As organizations plan for 2026 and beyond, the Laboratory Animal Housing Cage Market presents both operational leverage points and strategic choices. The forecast trajectory implies sustained demand, but the value of the market research lies in its ability to convert that broad expectation into segment-specific, regulation-aware, and competition-grounded guidance.
For facility operators and institutional buyers, the report informs specification decisions, replacement-cycle planning, and supplier evaluation by linking compliance requirements and welfare expectations to housing architecture choices. For equipment and system suppliers, it clarifies where differentiation is accruing—whether through ventilation performance, durability, digital integration, or multi-species versatility—and how competitive concentration shapes go-to-market positioning. For investors and strategic partners, the study provides a structured view of demand geography, material and application preferences, and the cadence of innovation activity that underpins near-term commercial opportunities.
The analysis also supports scenario planning. Because the market is shaped by research funding cycles, regulatory interpretation, and facility modernization timing, decision-makers benefit from models that test how changes in adoption velocity, compliance stringency, or regional research intensity alter demand outcomes. The full report embeds this flexibility into its forecasting and segmentation structure.
Why the Complete Study Matters
A preview can establish direction, but operational decisions require specificity. The complete Laboratory Animal Housing Cage Market research delivers the detailed segment breakdowns, regional demand context, application-level sizing, material-technology splits, and supplier-level competitive inputs that executives need to move from directional confidence to precise planning. It pairs quantitative rigor with qualitative insight, ensuring that forecasts are grounded in observable market structure and that competitive interpretation is tied to documented product, partnership, and event activity.
Most critically, the study is built to be used. Its segmentation logic, competitive mapping, and regulatory-context synthesis are designed to inform procurement specs, sourcing diversification, capital planning, and product strategy. For organizations operating in biomedical research, contract services, or laboratory infrastructure, the report transforms a complex, regulation-shaped market into a navigable strategic map.
Access the Full Intelligence
This preview has outlined the analytical scope, the macro trajectory, the regulatory and competitive context, and the decision-making value of the study. The full report extends this foundation into detailed segment breakdowns, supplier-level competitive analysis, and customizable forecasting frameworks that allow your organization to align strategy with the most relevant demand signals.
To access the complete dataset, segment-level intelligence, and competitive profiles that underpin this analysis, request the full report through our official research portal. The complete study provides the depth, granularity, and applied frameworks required to support confident 2026 planning and multi-year capital and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Laboratory Animal Housing Cage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Titanium Diboride Market Hits $44.1M in 2025, Set to Grow at 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
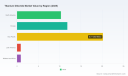
Navigating the Titanium Diboride Market: Strategic Intelligence for 2026 Decision-Makers
The global landscape for advanced ceramics is undergoing a quiet but fundamental transformation. At the center of this shift lies titanium diboride (TiB2), a material whose unique combination of hardness, electrical conductivity, and thermal stability is reshaping demand patterns across defense, semiconductor, and industrial manufacturing sectors. As organizations finalize their capital allocation and product roadmaps for 2026 and beyond, access to granular, forward-looking intelligence is no longer a luxury—it is a prerequisite for sustainable competitive advantage.
Our latest Titanium Diboride Market study, published by PW Consulting, is designed to meet this imperative. Spanning a historical analysis from 2020 through 2025 and a comprehensive forecast extending to 2032, this research translates complex market signals into an actionable strategic framework. Below, we outline the core architecture of the analysis, highlight the competitive dynamics currently reshaping the value chain, and explain why deepening your understanding of this niche—but rapidly evolving—market is a critical exercise for executive teams planning their next phase of growth.
Market Trajectory: From Steady Expansion to Strategic Inflection
The titanium diboride market has demonstrated resilient, compounding growth over the past half-decade. In 2020, total global market revenue stood at approximately 32.0 million USD. By 2025, that figure had climbed to 44.1 million USD—a trajectory that reflects both organic industrial adoption and the material's successful penetration into high-performance end-use segments. Looking ahead, our baseline forecast projects continued expansion, with market revenue expected to reach 45.28 million USD in 2026 and advance steadily toward 60.2 million USD by 2032. This long-view projection is anchored by an anticipated compound annual growth rate (CAGR) of 4.5 percent across the 2026-to-2032 forecast horizon.
These macroeconomic figures tell an important story, but they are only the starting point. The real strategic value lies in understanding how this growth is distributed across product types, application verticals, and geographic corridors—exactly the dimensions where competitive positioning can be won or lost. Market analysis at this level must move beyond headline numbers to examine the structural drivers: the maturation of bulk-grade production against the accelerating uptake of nanostructured formulations, the shifting allocation of demand across cutting tools, wear-resistant coatings, armor materials, refractory applications, electrodes and electrical contacts, composite materials, thermal barrier coatings, nuclear applications, and aerospace components, as well as the divergent growth tempos across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each of these segments carries its own pricing logic, supply constraints, and technology adoption curves, and our study maps them with precision.
Importantly, the market's growth profile is not uniformly distributed, and concentration patterns underscore this reality. The top three participants command a combined market share of 62.0 percent, while the top five extend that figure to 76.0 percent. This level of consolidation signals a market where scale, technology moats, and long-term customer relationships carry disproportionate weight—and where new entrants or expanding players must navigate an already crowded field with clear differentiation strategies.
Inside the Report: An Operational Playbook, Not a Static Snapshot
PW Consulting's Titanium Diboride Market study is structured to serve as a working reference for strategy, procurement, product development, and investment teams. Rather than offering a single trajectory, the report builds a multi-dimensional view of the market that connects demand fundamentals with supply-side realities, competitive behavior, and the broader industrial environment.
Key components of the analysis include:
- Segment-level deep dives: Detailed evaluation of how each product type and application category is evolving in terms of volume, value, technology requirements, and end-user adoption incentives. The analysis highlights where premium-grade materials are unlocking higher margins and where cost-optimized bulk supplies remain the dominant commercial vehicle.
- Regional market architecture: A geographically disaggregated assessment that examines demand intensity, manufacturing presence, trade flows, and localized supply constraints across all major regions. This section is designed to inform capacity siting decisions, partnership targeting, and market-entry prioritization.
- Competitive profiling and strategic positioning: In-depth company assessments that go beyond corporate descriptions to evaluate each player's product focus, geographic footprint, technology emphasis, and apparent strategic direction. The report contextualizes how established specialists and emerging capacity additions are reshaping share dynamics.
- Supply chain and input cost context: Examination of the material ecosystem that underpins titanium diboride production, including the role of boron-based feedstocks, energy intensity, and the operational impact of logistics and freight conditions on cost structures.
- Regulatory and environmental overlay: Analysis of how environmental considerations, mining and processing constraints, and compliance dynamics influence both upstream feedstock availability and downstream manufacturing economics.
- Technology and application horizon scanning: Identification of emerging use cases—such as additive manufacturing grades, advanced electronic sputtering targets, and next-generation armor and aerospace ceramics—that are expanding the addressable market and creating new value pools.
- Forecast scenarios and decision frameworks: Structured projections through 2032 that allow readers to stress-test assumptions around demand growth, competitive intensity, and input cost evolution, supporting both short-term operational planning and longer-range investment evaluation.
This integrated approach ensures that the study functions as more than a data repository. It is built to help decision-makers translate market signals into concrete actions: whether that means prioritizing a specific application vertical for product development, evaluating a potential partnership or acquisition, calibrating pricing strategy in a consolidating market, or assessing the viability of new capacity in a specific geographic corridor.
Competitive Dynamics: Specialists, Subscale Disruption, and Strategic Consolidation
The titanium diboride market is defined by a set of specialized producers whose capabilities are tightly aligned with specific end-use requirements. Understanding who these players are—and how they are positioning themselves—offers essential context for any strategic assessment of the market.
Europe remains home to several high-purity, technology-focused producers. Treibacher Industrie AG, based in Althofen, Austria, stands as a leading European source of high-purity titanium diboride powders and related hard material powders, serving industrial, aerospace, and electronics applications. Alongside it, H.C. Starck GmbH, part of the Mitsubishi Materials Group and headquartered in Goslar, Germany, is a prominent European producer of high-purity TiB2 powders and sputtering targets, with a strong presence in semiconductor, aerospace, and specialty chemistry markets. In a recent strategic move, H.C. Starck launched a new grade of titanium diboride powder tailored for additive manufacturing applications, with improved properties aimed at aerospace and automotive end-use sectors—a development that underscores the growing intersection between advanced materials and next-generation manufacturing processes.
In North America, the competitive picture blends established industrial material strength with specialized high-performance applications. 3M Company, through its Ceradyne subsidiary based in St. Paul, Minnesota, operates as a dominant supplier of TiB2-based defense armor, aerospace ceramics, and advanced materials, supported by long-standing military procurement relationships. Materion Corporation, headquartered in Mayfield Heights, Ohio, concentrates on high-purity TiB2 sputtering targets and specialty powders for semiconductor and thin-film deposition markets across North America and Europe—an application space where purity specifications and consistent quality are critical differentiators.
Japan continues to play a central role in specialty-grade material supply. Japan New Metals Co., Ltd., based in Toyonaka, Osaka, supplies specialty-grade TiB2 powders designed for electronics, precision tooling, semiconductor, and other high-value-added applications, with both domestic demand and export markets in scope.
China's manufacturing base adds significant volume and breadth to the global supply picture. Shandong Pengcheng Advanced Ceramics Co., Ltd., located in Zibo, Shandong, operates as a major Chinese producer of TiB2 ceramics, powders, and conductive ceramics, with applications spanning aluminum smelting cathodes, industrial cutting tools, and armor protection. Dandong Chemical Engineering Institute Co., Ltd. (DCEI), based in Dandong, Liaoning, produces titanium diboride alongside hexagonal boron nitride and amorphous boron powders, leveraging advanced processing technologies for a range of industrial applications. Together, these producers illustrate the dual nature of the market: a high-value, purity-sensitive segment driven by electronics, aerospace, and defense requirements, and a volume-oriented segment anchored in industrial tooling, wear applications, and cathode materials.
Worldwide Military Grade Titanium Disilicide Powder Market
Capacity and geographic expansion are already reshaping the competitive landscape. In July 2025, Kyocera Corporation acquired a titanium diboride ceramics manufacturing facility in South Korea, a move aimed at expanding production capacity and strengthening its market presence in the region. Such initiatives signal that established materials manufacturers are actively investing in geographic diversification and production scale, reinforcing the market's growth trajectory while simultaneously raising the bar for competitive differentiation.
Input Costs, Logistics, and Regulatory Currents: The Forces Shaping Margins
No strategic assessment of the titanium diboride market is complete without examining the upstream and environmental forces that influence both cost structures and supply reliability. Boron-based feedstocks sit at the heart of TiB2 production economics, and recent market intelligence points to several interconnected dynamics that buyers and producers alike must monitor.
Global boric acid prices exhibited a slightly declining trend in the first quarter of 2026, with spot prices in China recorded at 1,146 USD per metric ton in December 2025 amid relatively stable supply conditions. While a softening in feedstock pricing can ease input cost pressure in the near term, it does not eliminate the structural sensitivities that define this supply chain. Environmental regulations and mining costs continue to shape boric acid supply-side conditions for boron-based materials, introducing a persistent layer of uncertainty into cost forecasting. At the same time, supply chain disruptions and logistical challenges have influenced boric acid price movements across North America, Asia Pacific, and Europe, while environmental restrictions and freight rate fluctuations remain key factors affecting the overall cost structure of boron feedstock destined for TiB2 production.
For market participants, these dynamics carry direct strategic implications. Procurement teams must evaluate supplier resilience, inventory buffers, and geographic sourcing diversification in light of freight volatility and regulatory constraints. Producers need to factor energy intensity, environmental compliance, and logistics exposure into capital planning and pricing architecture. And executives designing market-entry or capacity-expansion strategies must account not only for demand momentum but also for the evolving complexity of the input cost environment that will ultimately determine margin sustainability.
Why This Research Matters for 2026 Strategy
As organizations move from planning cycles into execution, the titanium diboride market presents a clear case for informed, data-grounded decision-making. The combination of a consolidated competitive structure, differentiated application demand, evolving manufacturing technologies, and a feedstock environment shaped by logistics and regulatory pressures creates a setting where strategic clarity matters more than ever.
This study is designed to give executives, analysts, and operational leaders the kind of market visibility that supports confident action. It connects high-level growth trajectories with the granular segment and competitive intelligence required to build realistic scenarios, identify priority opportunities, and anticipate the shifts that will redefine value creation through 2032. Whether your focus is on expanding product portfolios, securing supply, evaluating partnership or acquisition targets, or positioning for geographic growth, the report offers the structured insight needed to move forward with precision.
For a complete view of the market size, segment dynamics, competitive profiles, and forward-looking forecasts underpinning this analysis, we invite you to access the full Titanium Diboride Market research. The detailed intelligence within is built to support the decisions that will define your organization's trajectory in the years ahead.
Titanium Diboride Market
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Tubing Set Market Hits $1,027.5M in 2025 with 4.12% CAGR to 2032
By PW Consulting, 2026-09-16
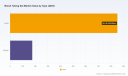
Strategic Intelligence in the Blood Tubing Set Market: Navigating Growth and Regulation in 2026
The global medical device landscape is undergoing a period of nuanced transformation, and few segments illustrate this complexity better than the Blood Tubing Set Market. As healthcare systems worldwide grapple with aging demographics, rising prevalence of chronic kidney disease, and increasingly stringent regulatory frameworks, the demand for reliable, high-performance extracorporeal blood circuits has never been more critical. For executives, procurement leaders, and investment analysts, understanding the trajectory of this market is not merely an academic exercise—it is a foundational requirement for strategic planning in 2026 and beyond.
At PW Consulting, we have released a comprehensive new study designed to cut through the noise and provide actionable intelligence. This article serves as an introduction to those findings, highlighting the strategic value the research offers to enterprises operating within or adjacent to the dialysis and blood transfusion ecosystems. While we preview the macro trends and competitive dynamics here, the full depth of segment-level analysis, regional breakdowns, and proprietary forecasts is reserved for our detailed report. Readers seeking to benchmark their position or identify high-yield opportunities are encouraged to consult the complete intelligence package.
Blood Collection Tubes Market
Market Trajectory and Core Financial Indicators
The Blood Tubing Set Market has demonstrated steady, predictable growth over the past half-decade, reflecting the essential nature of the products involved. Analysis of historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, moving from a baseline of approximately 812.35 million USD in 2020 to 1,027.5 million USD by 2025. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Blood Tubing Set Market
Our forecast models indicate that the market will continue to expand, driven by volume growth in dialysis procedures and incremental improvements in tubing set durability and biocompatibility. The projected compounding annual growth rate (CAGR) for the forecast period stands at 4.12 percent. This rate suggests a mature but resilient market environment, where growth is less about explosive disruption and more about steady volume expansion, technological refinement, and strategic consolidation. By the end of the forecast horizon in 2032, total market revenue is anticipated to reach significant new thresholds, offering clear pathways for stakeholders who can navigate supply chain complexities and regulatory compliance effectively.
For decision-makers in 2026, this trajectory implies several strategic imperatives. First, the market is not poised for volatile spikes but rather for sustained, manageable growth, requiring long-term capacity planning rather than short-term speculation. Second, the financial metrics underscore the importance of cost efficiency in manufacturing and procurement, particularly given the material cost dynamics inherent in medical-grade production.
Product Segmentation and Clinical Applications
Understanding where value is generated within the Blood Tubing Set Market is critical for targeted strategy. The market is broadly segmented by patient demographics, distinguishing between adult and pediatric applications. Given the higher prevalence of end-stage renal disease in adult populations, the adult segment naturally commands the majority of revenue share. However, the pediatric segment, while smaller in volume, often commands different specifications regarding priming volume, biocompatibility, and safety features. A successful product portfolio must address both segments with appropriate engineering and positioning.
Application-wise, the market is anchored by two primary channels: dialysis centers and hospitals & clinics. Dialysis centers represent the dominant setting for blood tubing set utilization, reflecting the chronic nature of hemodialysis treatments and the high frequency of disposable circuit replacement required per patient per week. Hospital and clinic environments also constitute a vital channel, particularly for acute dialysis scenarios, surgical procedures requiring extracorporeal circulation, and specialized care units. Each channel presents distinct procurement cycles, reimbursement pathways, and regulatory oversight requirements.
Our report provides granular analysis of these segmentation splits, helping organizations identify which sub-segments offer the best alignment with their manufacturing capabilities or distribution strengths. Rather than applying a one-size-fits-all strategy, the data suggests that tailored approaches based on application setting and patient age group yield significantly better margins and customer retention.
Competitive Landscape: Key Players and Strategic Moves
The Blood Tubing Set Market is characterized by a concentrated competitive environment where established medical device manufacturers leverage specialized product portfolios and regulatory expertise to maintain market share. Several key companies define the landscape, offering machine-specific and system-agnostic solutions that cater to the diverse needs of hemodialysis providers.
Nipro Corporation, headquartered in Osaka, Japan, has established a strong presence through its NiproSet blood tubing sets. These products are notable for being machine-specific for hemodialysis, featuring FDA-tested components that emphasize compatibility and safety. Nipro’s strategy highlights the value of close integration with dialysis equipment manufacturers, ensuring that tubing sets perform optimally within specific system configurations.
B. Braun Melsungen AG, based in Melsungen, Germany, offers the Streamline Airless System Hemodialysis Bloodlines and DiaStream bloodline systems. These solutions focus on reducing air embolism risks and improving hemodynamic stability during treatment. B. Braun’s approach underscores the importance of engineering innovations that directly reduce clinical risks, a key selling point in procurement decisions made by hospital administrators and nephrology directors.
Fresenius Medical Care AG, with headquarters in Bad Homburg vor der Höhe, Germany, provides the CombiSet SMARTECH and other blood tubing sets tailored for hemodialysis machines. As a global leader in dialysis care, Fresenius leverages its extensive clinical network and integrated service model to promote its consumables, reinforcing brand loyalty and standard-setting within care facilities.
Recent developments in the competitive and regulatory space underscore the need for vigilance. In April 2026, B. Braun Medical Inc. issued an urgent medical device correction regarding the Streamline Airless System Hemodialysis Bloodlines and B3 Low Volume Bloodlines. The correction addressed potential microbubble and leakage risks, with updates issued following FDA MedWatch alerts. Such events serve as a stark reminder that even mature products require continuous quality monitoring, rapid response protocols, and transparent communication with the regulatory community. For competitors and customers alike, these corrections influence purchasing confidence and may shift volume toward alternative suppliers who can demonstrate robust quality management systems.
Regulatory Environment and Clinical Compliance
The Blood Tubing Set Market operates within a tightly regulated framework that shapes product development, market entry, and ongoing compliance. Hemodialysis blood tubing sets are classified as Class II devices, subject to FDA 510(k) requirements for demonstrating substantial equivalence to existing predicates. This regulatory pathway demands rigorous documentation, clinical performance data, and quality system adherence, creating barriers to entry that protect established players while ensuring patient safety.
Reimbursement dynamics also play a pivotal role in market behavior. Hemodialysis blood tubing sets are covered under Medicare Part B reimbursement codes for dialysis procedures, linking device utilization directly to federal payment structures. Changes in coverage policies or coding updates can ripple through demand patterns, affecting volume projections and pricing strategies. Stakeholders must stay attuned to Centers for Medicare & Medicaid Services (CMS) national coverage determinations, which remain active and influential throughout 2026.
International standards further complicate the compliance landscape. Blood tubing sets must comply with ISO 10993 biocompatibility standards for blood contact, ensuring that materials do not induce adverse immune or thrombotic responses. Additionally, all blood tubing sets are single-use devices sterilized via gamma irradiation or ethylene oxide prior to market release, as mandated by FDA premarket notification guidance. These sterilization requirements impact production logistics, facility design, and cost structures, particularly regarding the medical-grade PVC tubing that forms the core of many sets. Unit costs for such tubing can vary between 5 and 15 USD per set depending on volume and customization, adding a layer of financial sensitivity that procurement teams must manage carefully.
Strategic Insights for 2026 Decision-Making
The intersection of market growth, competitive dynamics, and regulatory requirements creates a complex environment where strategic foresight is paramount. For manufacturers, the key challenge lies in balancing innovation with compliance, ensuring that new product features do not inadvertently trigger additional regulatory scrutiny or quality issues. For distributors and healthcare providers, the focus shifts to supply chain resilience, vendor reliability, and cost optimization without compromising patient safety.
Several actionable themes emerge for 2026:
- Portfolio Optimization: Companies should assess whether their tubing set offerings adequately address the divergent needs of adult versus pediatric patients and the specific requirements of dialysis centers versus hospital settings. Consolidating around high-performing, compliant products while phasing out underperforming SKUs can sharpen competitive positioning.
- Regulatory Preparedness: With Class II classification and ISO 10993 compliance as baseline requirements, organizations must maintain robust documentation and quality management systems. Proactive engagement with regulators and continuous monitoring of safety alerts, such as the 2026 B. Braun correction, can mitigate reputational risk and inform product improvement cycles.
- Cost and Supply Chain Management: Given the material cost variability in medical-grade PVC and the sterilization requirements, procurement strategies should factor in volume commitments, supplier diversification, and logistics stability. Long-term contracts with reliable raw material suppliers can help smooth out unit cost fluctuations.
- Reimbursement Alignment: Understanding how Medicare Part B codes and CMS determinations affect demand is essential for revenue forecasting. Aligning product features with reimbursable procedure codes can enhance market access and encourage adoption in cost-sensitive care settings.
What the Full PW Consulting Study Delivers
The insights outlined above represent only the opening chapter of our comprehensive Blood Tubing Set Market research. The full report goes much deeper, offering a level of granularity that enables precise strategic planning and investment analysis. Readers who access the complete study will find detailed segmentation breakdowns by region and type, forward-looking revenue forecasts through 2032, and a thorough examination of market concentration metrics. The report also includes analysis of industry context, covering regulatory shifts, reimbursement updates, material cost trends, and sterilization practices that impact total cost of ownership.
Furthermore, the study provides an in-depth competitive benchmarking section, profiling key players, their product specifications, recent developments, and strategic positioning. This allows companies to benchmark their own offerings, identify gaps in their portfolios, and anticipate competitor moves with greater accuracy. The research is designed to serve a wide range of stakeholders, from product managers and supply chain directors to investors and policy analysts, delivering a cohesive narrative backed by rigorous data analysis.
Conclusion
The Blood Tubing Set Market in 2026 is a landscape of steady growth, concentrated competition, and rigorous compliance demands. For organizations operating in this space, the ability to interpret market signals, anticipate regulatory changes, and align product strategies with clinical and reimbursement realities will determine long-term success. PW Consulting’s latest market research provides the strategic intelligence needed to navigate this environment with confidence, transforming raw data into clear, actionable directions. To unlock the full spectrum of insights, segmentation details, and competitive analysis, we invite you to explore the complete report and integrate its findings into your 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Concrete Mixer Market: Why Our 2026 Industry Report Matters
In an era where industrial equipment markets are shaped by rapid technological adoption, shifting regulatory landscapes, and volatile supply chain dynamics, capital allocation and product roadmap decisions require more than surface-level market sizing. The global concrete mixer market stands at a critical inflection point. Infrastructure stimulus programs, residential and commercial construction rebounds, and the gradual electrification of heavy-duty mobile equipment are converging to reshape competitive positioning and demand patterns across every major geography. Our newly released Concrete Mixers Market research was designed specifically for executives, investors, and procurement leaders who need actionable clarity rather than retrospective summaries. This overview outlines the strategic value embedded in the full study and explains how decision-makers can leverage its findings to navigate the 2026 operating environment with confidence.
A Market in Transition: Trajectory, Scale, and the Decision-Maker’s Lens
Over the past five years, the concrete mixer sector has demonstrated steady expansion against a backdrop of cyclical construction demand and component cost pressures. Historical data from 2020 through 2025 reflects a market that grew from approximately 4.78 billion USD to 6.2 billion USD, navigating brief contractions while maintaining long-term momentum. Looking ahead, the forecast period from 2026 through 2032 projects continued growth at a compound annual growth rate of 4.5 percent, with projected revenue scaling toward 8.51 billion USD by the end of the forecast window. These figures establish a clear baseline: demand is not merely rebounding, it is structurally evolving.
For strategy teams, the value of these numbers lies not in the headline but in the underlying drivers. The transition from legacy mechanical systems to smarter, lighter, and more efficient mixing platforms is reshaping unit economics. Simultaneously, the competitive intensity of the sector is evident in market concentration metrics, where the top three players account for roughly 45 percent of revenue and the top five capture approximately 60 percent. Such concentration suggests both the presence of established incumbents with scale advantages and meaningful room for disruptors targeting niche applications, regional gaps, or specific operational pain points such as licensing constraints, emissions compliance, and on-site precision.
Raw material volatility, particularly in steel pricing, has introduced meaningful variability in production costs for critical components including drums and chassis. At the same time, procurement validation processes from state departments of transportation continue to standardize approved admixtures and accessories, reinforcing the importance of compliance-ready equipment specifications. Regulatory signals also warrant close attention. In key jurisdictions, energy policy assessments have highlighted that commercially viable zero-emission concrete mixer trucks remain unavailable as of 2026, underscoring the strategic horizon for electrification and alternative powertrain investments. These dynamics do not merely influence costs; they redefine which product architectures will win procurement approvals, fleet adoption, and long-term service contracts.
Inside the Research: Operational Content Built for Execution
This study was structured to support concrete decision-making rather than abstract observation. Readers will find a comprehensive mapping of the market across the primary axes that matter to product planning, channel strategy, and competitive positioning. The report examines segment-level demand characteristics across mixer architectures, application environments, and regional operating conditions, providing a structured lens through which to evaluate where growth is most durable and where margin pressure is most likely to emerge.
Concrete Mixers Market
Beyond segmentation, the analysis delivers an actionable view of the competitive landscape. Profiles of leading manufacturers and emerging specialists are synthesized to highlight differentiators in product design, service ecosystems, and market focus. Rather than treating competition as a static roster, the research connects company positioning to real-world developments that shape buyer preferences. This includes attention to product launches, technology integrations, and event-driven showcases that signal where incumbents are doubling down and where new entrants are carving out defensible positions.
The report also integrates market dynamics that frequently fall outside conventional sizing exercises but carry direct implications for commercial strategy. Material cost behavior, regulatory developments, procurement validation practices, and reimbursement frameworks are examined for their influence on demand elasticity, total cost of ownership, and equipment selection criteria. By linking these forces to segment and regional behavior, the study equips readers to anticipate where pricing power may shift, where specification requirements may tighten, and where operational efficiency will become a decisive competitive advantage.
Worldwide Self Loading Concrete Mixers Market
Competitive Landscape: Leaders, Specialists, and the Shape of Differentiation
The competitive field in concrete mixing equipment is defined by a mix of global heavy-equipment brands, regional specialists, and technology-focused innovators. Large-scale manufacturers continue to anchor the market with broad product portfolios spanning mixer trucks, batching systems, and heavy-duty mobile equipment. Their strength lies in distribution reach, fleet-scale support, and the ability to align mixing solutions with broader construction and infrastructure workflows. For buyers managing large pours, long haul distances, and stringent uptime requirements, these players often serve as default procurement options.
At the same time, a distinct layer of specialists is reshaping expectations around on-site precision, operational flexibility, and regulatory convenience. Volumetric mixing approaches, portable continuous systems, and lightweight configurations are gaining relevance among residential, utility, and mid-sized commercial producers who prioritize exact dosage control, reduced mobilization constraints, or simplified licensing requirements. In this context, product innovation is not only about durability or capacity; it is increasingly about reducing friction in the customer’s operating model. Innovations that improve visibility during transport, enable smaller crews, or reduce licensing burden are becoming meaningful differentiators in competitive bids and repeat purchase decisions.
Recent developments reinforce this direction. Attention to electrification and hybrid platforms reflects a growing demand for efficiency and emissions reduction, even in the absence of fully commercialized zero-emission mixer trucks in some major markets. Parallel innovation in real-time monitoring and drum-level intelligence points to a broader shift toward connected equipment, where transport visibility and quality control are integrated into the hardware itself. Showcase activity at major industry events has also highlighted refreshed model lines with advanced drivetrain and chassis characteristics, signaling that conventional heavy-duty platforms are being refined rather than abandoned. Collectively, these moves illustrate a market where incumbents and challengers are competing on multiple fronts: scale, specialization, technology, and total cost of ownership.
2026 Decision Framework: Turning Macro Visibility into Strategic Action
For executives evaluating market participation, capacity expansion, product development, or procurement strategy, the immediate question is not whether the concrete mixer market is growing, but where the most defensible opportunities reside in 2026 and beyond. The research is built to answer that question through disciplined analysis rather than generalized optimism. Several strategic themes emerge consistently across the data and qualitative context.
- Segment selection matters more than aggregate growth. Demand patterns differ substantially across mixer types and application environments. Organizations that align product portfolios with the most stable and highest-value use cases can better withstand component cost fluctuations and cyclical construction variance.
- Total cost of ownership is becoming a decisive differentiator. With steel price volatility affecting component costs and regulatory signals pointing toward future emissions constraints, buyers are increasingly weighing operating efficiency, maintenance burden, and compliance readiness alongside upfront price.
- Technology adoption is moving from optional to expected. Real-time monitoring, hybrid or electrified platform exploration, and lightweight designs that simplify deployment are beginning to influence purchasing criteria, particularly among producers seeking leaner operations and reduced licensing friction.
- Regional strategy requires localized insight. Demand concentration, infrastructure priorities, and procurement standards vary widely by geography. A successful market approach depends on understanding which regions offer the most reliable demand pull and which segments are most sensitive to local specification and validation requirements.
The full study expands each of these themes into operational guidance. It connects market size and growth expectations to segment-level behaviors, maps the strategic implications of recent product and policy developments, and highlights where competitive pressure is likely to intensify. For investors, the analysis supports more precise evaluation of market entry timing, end-market exposure, and technology risk. For manufacturers and distributors, it informs product planning, regional prioritization, and the design of service offerings that align with evolving buyer expectations. For procurement and fleet leaders, it sharpens the criteria for specification, supplier selection, and lifecycle cost modeling.
Why the Full Report Is the Strategic Next Step
A market overview can signal direction, but it cannot replace the granularity required to act. The complete Concrete Mixers Market research translates macro trajectory into decision-grade intelligence by combining validated sizing and forecast data with segment behavior, competitive profiling, and dynamic market forces. It is designed to reduce uncertainty around which product strategies, geographic priorities, and customer segments deserve disproportionate attention in the 2026 planning cycle.
Readers who require only high-level context may find this summary useful as a directional reference. Leaders responsible for capital deployment, product roadmaps, bidding strategy, or portfolio optimization will benefit from the deeper segmentation, competitive intelligence, and operational context available in the full publication. The report also provides a structured basis for scenario planning, helping teams prepare for multiple futures rather than betting on a single narrative.
To access the complete analysis, including detailed market sizing, forecast pathways, segment assessments, and the full competitive and dynamic landscape, visit the source page for the Concrete Mixers Market research. The complete report equips decision-makers with the depth required to convert market signals into strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Concrete Mixers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ganesh Sthapana marks the joyous beginning of Ganesh Chaturthi celebrations, when devotees welcome Lord Ganesha into their homes as an honored guest. Performed with devotion and following the correct vidhi (ritual procedure), this puja is believed to invite prosperity, wisdom, and the removal of obstacles into the household for the days the idol resides there. If you're planning to perform Ganesh Sthapana puja vidhi at home this year, this guide walks you through everything — from preparation to the final aarti — so you can conduct the ritual correctly and with confidence.
What is Ganesh Sthapana?
Ganesh Sthapana literally means the "establishment" or "installation" of Lord Ganesha. It is the ceremonial act of bringing home an idol of Ganesha and installing it with proper rituals on Ganesh Chaturthi, the day believed to mark Lord Ganesha's birth. The idol is worshipped daily for a period ranging from one and a half days to eleven days, depending on family tradition, before being immersed in water during Ganesh Visarjan.
The sthapana is not merely a symbolic placement — it involves invoking the deity's presence (prana pratishtha), offering a formal welcome (shodashopachara puja), and creating an environment of purity and devotion in the home.
Significance of Ganesh Sthapana
Lord Ganesha is worshipped first in Hindu tradition before any other deity, as he is considered the remover of obstacles (Vighnaharta) and the god of wisdom, prosperity, and new beginnings. Installing him at home during Ganesh Chaturthi is believed to:
- Bring good fortune and remove hurdles in ongoing or upcoming endeavors
- Invite wisdom, intellect, and clarity into the household
- Strengthen family bonds through shared festive rituals
- Mark an auspicious start to new projects, businesses, or ventures
Choosing the Right Muhurat
Timing matters in Vedic rituals, and Ganesh Sthapana is traditionally performed during the Madhyahna Kaal (midday period) on Ganesh Chaturthi, since this is considered the time of Lord Ganesha's birth. Many families also prefer to avoid Rahu Kaal and other inauspicious periods on that day. Since the exact muhurat timings shift every year based on the Hindu calendar, it's best to confirm the current year's auspicious timing with a qualified pandit or a reliable panchang before you begin.
Items Required for Ganesh Sthapana Puja
Gathering everything beforehand ensures the ritual flows smoothly without interruption. Here's what you'll typically need:
- Ganesha idol (clay/eco-friendly idols are preferred for easy immersion)
- A wooden platform (chowki) covered with a clean red or yellow cloth
- Fresh flowers, garlands, and durva grass (an offering especially dear to Ganesha)
- Red vermilion (sindoor) and turmeric (haldi)
- Akshat (unbroken rice grains)
- Panchamrit (a mix of milk, curd, honey, ghee, and sugar)
- Coconut, betel leaves (paan), and betel nuts (supari)
- Modak or laddu (Ganesha's favorite sweet)
- Incense sticks (agarbatti), camphor (kapoor), and a diya with ghee or oil
- A kalash (copper or brass pot) filled with water, topped with mango leaves and a coconut
- Gangajal (holy water)
- A bell (ghanti)
- Fresh fruits and a plate for aarti
Step-by-Step Ganesh Sthapana Puja Vidhi
1. Purify the Space
Begin by cleaning the area where the idol will be installed. Sprinkle Gangajal around the space to purify it spiritually. Decorate the chowki with a fresh cloth, rangoli, and flowers.
2. Take a Sacred Bath and Wear Clean Clothes
Before starting the puja, take a bath and wear fresh, preferably traditional, clothing. This reflects the purity required to invoke the deity.
3. Place the Idol
Gently bring the Ganesha idol home, ideally facing north or east, and place it on the decorated chowki. Many families welcome the idol into the house with a small aarti at the doorstep before installation.
4. Perform Sankalp
Sit facing the idol, take water, rice, and flowers in your right hand, and take a sankalp (a formal vow) stating your intention to perform the puja, along with the date, time, and purpose.
5. Invoke Prana Pratishtha
This is the most important step of the sthapana — invoking life-force into the idol. Chant the prana pratishtha mantras (a pandit's guidance is recommended here) while offering akshat and flowers, symbolically inviting Lord Ganesha's divine presence into the murti.
6. Offer Shodashopachara Puja (16-Step Worship)
Traditionally, the puja includes sixteen ritual offerings:
- Aavahan (invocation)
- Aasan (offering a seat)
- Paadya (washing the feet)
- Arghya (offering water)
- Aachaman (sipping water)
- Snan (ceremonial bath with panchamrit and water)
- Vastra (offering clothes)
- Yajnopavit (sacred thread, if applicable)
- Chandan (sandalwood paste)
- Pushpa (flowers)
- Dhoop (incense)
- Deep (lamp)
- Naivedya (food offerings like modak)
- Tambool (betel leaf and nut)
- Dakshina (offering)
- Aarti (final worship with lamp)
7. Offer Durva Grass and Modak
Durva grass and modak hold special significance in Ganesha worship. Offer 21 blades of durva grass along with modak or laddus, as these are considered Ganesha's favorite offerings.
8. Chant Mantras and Aarti
Recite the Ganesh mantra — "Om Gan Ganapataye Namah" — 108 times if possible, followed by the traditional "Jai Ganesh Aarti." Ring the bell throughout the aarti and light camphor as the final offering.
9. Distribute Prasad
Conclude the puja by distributing prasad (modak, fruits, or sweets) among family members and guests present.
Daily Puja During the Festival
Once installed, Lord Ganesha is worshipped every morning and evening with a simple aarti, flowers, and naivedya until the day of visarjan. Maintaining cleanliness around the idol and offering fresh flowers daily is considered important throughout the festival.
Tips for a Smooth Ganesh Sthapana
- Choose an eco-friendly clay idol to ensure a safe and environmentally responsible visarjan later
- Keep all puja items ready a day in advance to avoid last-minute rush
- If performing the puja without a pandit, familiarize yourself with the mantras beforehand or keep a mantra booklet handy
- Maintain the sanctity of the space by avoiding non-vegetarian food and alcohol in the house during the festival days
- Involve family members, especially children, in small tasks like arranging flowers or decorating the chowki to make it a shared experience
Conclusion
Performing Ganesh Sthapana puja vidhi at home is a beautiful way to invite Lord Ganesha's blessings into your household and set a positive tone for the festive season. While the steps outlined above follow traditional practice, engaging an experienced pandit can help ensure the rituals, mantras, and muhurat are followed with complete accuracy — offering peace of mind along with the spiritual benefits of a correctly performed puja.
For a hassle-free Ganesh Sthapana at home, you can book a verified, experienced pandit through BookMyPanditJee, who will guide you through every ritual with the correct mantras and vidhi.
PW Consulting: Financial Planning Software Market Hits $3.85B in 2025, 15.72% CAGR to $10.66B by 2032
By PW Consulting, 2026-09-16
The Financial Planning Software Market: Strategic Intelligence for 2026 Enterprise Decisions
The financial planning software market has evolved from a niche utility into a central nervous system for wealth management, corporate finance, and advisory practices. As organizations navigate an environment defined by rapid technological adoption, tightening compliance frameworks, and shifting client expectations, the ability to make informed technology investments is no longer optional. This market research report delivers a comprehensive, data-grounded examination of the sector, equipping executives, procurement leaders, and strategic planners with the intelligence required to position their organizations ahead of the curve in 2026 and beyond.
Market Trajectory and the Scale of Opportunity
Understanding where the market stands today requires a clear view of its historical momentum and forward-looking trajectory. Over the past half-decade, the financial planning software sector has demonstrated consistent expansion, reflecting broader digitization trends across financial services and corporate finance functions. The market's valuation has progressed steadily from approximately 2.28 billion USD in 2020 to an estimated 3.85 billion USD in 2025, underscoring a compound annual growth pattern that signals both industrial maturation and sustained demand.
Projecting forward, the sector is positioned to accelerate through the end of the decade. Current forecasts indicate that market revenue will surpass 4.37 billion USD in 2026, climbing progressively to reach roughly 10.66 billion USD by 2032. This growth is anchored by a projected CAGR of 15.72 percent across the forecast horizon, a rate that reflects not merely incremental adoption but a structural shift in how financial planning is executed, delivered, and integrated into broader operational workflows. For enterprise decision-makers, this trajectory carries a clear implication: the window for evaluating, selecting, and deploying next-generation planning platforms is actively open, and delay carries measurable competitive risk.
The scale of this expansion is not uniform across all segments, nor is it driven by a single catalyst. Growth is being distributed across multiple vectors, including platform modernization, service-led implementation and advisory models, and the broadening application of planning tools beyond traditional budgeting into scenario modeling, risk assessment, and advanced analytics. The report maps these vectors in detail, enabling buyers to distinguish between headline growth and the specific demand pockets most relevant to their operational context.
What This Report Delivers: Operational Intelligence for Strategic Planning
Market sizing alone does not inform procurement decisions or product roadmaps. Executives require a granular understanding of how the market is structured, who is competing, what regulatory constraints shape deployment, and where innovation is converging with practical utility. This research report is designed to translate macro-level trends into actionable strategic guidance.
Investment Management Software Market
Comprehensive Segmentation and Use-Case Mapping
The analysis dissects the market across multiple dimensions, providing a structured view of how demand is distributed across platform types, service offerings, and functional applications. Rather than presenting static splits in isolation, the report contextualizes each segment against adoption drivers, pricing dynamics, integration requirements, and implementation complexity. Decision-makers will gain clarity on which planning functionalities are seeing the strongest institutional traction, how platform versus service spending patterns differ across organization sizes, and where complementary capabilities are creating bundling opportunities or competitive differentiation.
Competitive Landscape and Vendor Positioning
The report profiles the dominant and emerging players shaping the market, examining their strategic focus, product philosophies, and recent moves that signal where the industry is heading. Key companies include Envestnet, eMoney Advisor, RightCapital, SS&C Technologies, and Orion Advisor Technology, each bringing distinct approaches to financial planning software. Envestnet's MoneyGuide platform emphasizes goals-based and comprehensive planning integrated with wealth management workflows. eMoney Advisor centers on cash-flow-based and goals-based planning, supported by client portals and collaborative planning tools. RightCapital distinguishes itself through tax-efficient planning, scenario analysis, and advisor productivity enhancements. SS&C Technologies offers Black Diamond wealth solutions, embedding financial planning modules within portfolio management and billing ecosystems. Orion Advisor Technology provides a planning platform tied to practice management and advisor reporting.
These profiles are not merely descriptive. The report evaluates each vendor's positioning relative to market demand, integration depth, compliance readiness, and innovation cadence. By mapping vendor strategies against buyer priorities, the analysis helps organizations shortlist candidates based on fit rather than brand recognition alone.
Recent Developments and Innovation Signals
Speed of iteration is a critical differentiator in software markets, and the financial planning sector is no exception. The report tracks recent product launches, platform enhancements, and ecosystem expansions that reveal where vendors are investing. Notable activity includes Envestnet's March 2026 launch of MoneyGuide Dash, designed to simplify and streamline the planning experience with modernized capabilities, followed by May 2026 announcements around AI-driven data automation and deeper MoneyGuide integration into proposal workflows, client records, and planning processes at the Elevate 2026 conference. Earlier, the R4 2025 release introduced tax management insights integrated into proposal strategy modification workflows.
eMoney Advisor has similarly moved to strengthen collaborative and extensibility features, including the April 2026 introduction of CoPlanner for team-based financial planning and decision-making, and a October 2025 platform enhancement that launched a new developer site for API integrations supporting market extensions. These developments illustrate a broader pattern: vendors are racing to reduce manual friction, embed intelligence into planning workflows, and open their platforms to third-party innovation. The report analyzes what these moves mean for buyers evaluating long-term platform viability and integration roadmaps.
Market Dynamics: Regulation, Security, and the Compliance Imperative
The financial planning software market does not operate in a vacuum. Regulatory expectations, data protection requirements, and fiduciary standards are now integral to platform selection and deployment. The report dedicates substantial attention to the compliance landscape, translating regulatory complexity into practical procurement considerations.
Across the sector, platforms are expected to meet rigorous security and documentation standards. IRS Publication 4557 sets the benchmark for client data handling, requiring SOC 2 Type II certification and Written Information Security Plan documentation for software that manages sensitive financial information. These requirements are not optional add-ons; they are baseline expectations that influence vendor eligibility, implementation timelines, and ongoing operational risk. The report outlines how leading platforms are structuring their compliance postures and what questions buyers should raise during due diligence.
Simultaneously, fiduciary and disclosure obligations continue to shape software design. Regulation Best Interest compliance features are increasingly embedded within planning tools to support fiduciary disclosure standards enforced by the SEC, ensuring that recommendations and planning outputs align with regulatory expectations. U.S. data storage and protection also must comply with SEC and FTC standards for financial data requests and safeguarding, adding another layer of scrutiny to infrastructure decisions.
Beyond U.S. frameworks, data privacy laws are tightening globally, with GDPR and related regimes demanding enhanced guardrails even for North American users whose data may intersect with international systems or multi-jurisdictional operations. The report examines how these regulatory pressures are influencing vendor architectures, data residency options, and the broader risk calculus for organizations selecting planning software. For buyers, the takeaway is clear: compliance capability is now a core component of value, not a peripheral checkbox.
Why This Research Matters for 2026 Decision-Making
Enterprise leaders face a crowded field of vendors, a fast-moving innovation cycle, and a compliance environment that rewards diligence. In this context, comprehensive market intelligence serves as a force multiplier. The report enables decision-makers to triangulate three critical questions: where is the market going, who is best positioned to serve specific organizational needs, and what capabilities must a platform demonstrate to remain viable over the implementation lifecycle?
The strategic value of this research extends across multiple functions. Procurement and technology teams gain a structured framework for evaluating platform types, service models, and functional coverage against internal requirements. Finance and advisory leaders receive insight into which planning applications are gaining institutional traction and how those applications align with evolving workflow priorities. Executive teams benefit from a competitive landscape view that highlights vendor strategy, innovation velocity, and concentration dynamics, supporting more confident investment and partnership decisions.
Financial Planning Software Market
Market concentration data further contextualizes the competitive environment. With the top three providers accounting for approximately 34.5 percent of market share and the top five reaching roughly 48.2 percent, the market exhibits meaningful but not prohibitive concentration. This structure suggests both the presence of established incumbents with scaled capabilities and sufficient room for specialized providers to compete on differentiation, niche functionality, and integration depth. The report explores how this balance shapes vendor negotiations, switching considerations, and the incentives that drive ongoing product development.
Aligning Technology Investment with Operational Reality
Selecting financial planning software is not a purely technical exercise. It intersects with practice management, advisor productivity, client experience, data governance, and long-term scalability. The report emphasizes the importance of aligning platform capabilities with operational realities, including team collaboration models, proposal and workflow integration, tax and scenario analysis needs, and the demand for transparent, client-facing planning experiences.
As platforms incorporate AI-driven automation, enhanced data integration, and richer collaboration features, the definition of an effective planning environment is expanding. Organizations that evaluate vendors against a comprehensive set of criteria, rather than isolated feature lists, are better positioned to realize return on investment and avoid costly rework. The research provides the comparative context needed to make those evaluations systematically.
Conclusion: Positioning for the Next Phase of Market Growth
The financial planning software market is entering a phase defined by accelerating adoption, intensifying competition, and rising expectations for security, compliance, and workflow intelligence. With a robust growth trajectory and a diverse set of vendors pursuing distinct strategic angles, the opportunity for organizations to strengthen their planning capabilities is substantial, but so is the complexity of navigating the landscape.
This market research report offers the depth, structure, and competitive context required to move from uncertainty to informed action. It translates macro growth signals into segment-level insight, maps vendor strategies against buyer priorities, and frames regulatory demands as integral to platform evaluation. For executives and planners preparing for 2026 and the years that follow, the report provides the intelligence foundation necessary to make technology decisions with confidence, precision, and strategic foresight.
To access the complete analysis, including detailed segmentation breakdowns, vendor comparisons, regulatory mapping, and forward-looking scenario context, we invite you to explore the full report. The complete intelligence package is designed to support procurement planning, vendor selection, and strategic roadmap development with the rigor that today's financial planning environment demands.
For detailed analysis of this topic, please visit the official page: Financial Planning Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Garbage Disposer Market to Reach $302.53 Million by 2032, 5.0% CAGR
By PW Consulting, 2026-09-16
Navigating the Garbage Disposer Market: Strategic Intelligence for 2026 and Beyond
The global waste management landscape is undergoing a structural transformation, driven by tightening environmental regulations, evolving consumer expectations, and rapid technological integration across residential and commercial kitchen ecosystems. At the center of this shift lies the garbage disposer market, a category that has quietly transitioned from a basic utility fixture to a strategically relevant component of sustainable infrastructure and appliance portfolios. As organizations map out capital allocation, product development pipelines, and regional expansion strategies for 2026, the need for precise, forward-looking market intelligence has never been more critical.
Our latest market research initiative delivers a comprehensive, data-grounded assessment of the garbage disposer industry, designed specifically to support executive decision-making, competitive positioning, and risk-managed growth planning. This overview outlines the strategic architecture of the study, highlights the macro-economic trajectory shaping the sector, and demonstrates how the full intelligence suite can be deployed to accelerate 2026 strategic execution.
Market Trajectory and Macro-Economic Context
The garbage disposer market has demonstrated consistent, measurable expansion over the past half-decade, reflecting broader trends in residential renovation, commercial kitchen upgrade cycles, and municipal waste diversion mandates. Historical performance from the early 2020s through the base year of 2025 reveals a steady revenue climb, supported by both replacement demand and incremental new installations across mature and emerging consumer markets.
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of approximately 5.0 percent. This trajectory is anchored by several converging forces: sustained housing and remodeling activity, growing adoption of high-rotation-speed disposal units that align with advanced wastewater treatment capabilities, and regulatory tailwinds that favor on-site food waste reduction over landfill dependency. Revenue forecasts across the horizon indicate a clear upward inflection, with market size expanding from the 2026 baseline toward a materially larger footprint by the early 2030s.
For strategic planners, this growth profile is not merely a top-line statistic. It signals a market that is scaling predictably enough to justify product investment and distribution expansion, yet dynamic enough to reward players who can accurately segment demand, anticipate regulatory shifts, and align product engineering with end-user performance expectations. Understanding where value is created across this expansion window is essential for prioritizing R&D budgets, setting pricing architectures, and determining go-to-market timing.
Structural Drivers Shaping Competitive Positioning
The contemporary garbage disposer market is being reshaped by a blend of environmental policy, infrastructure capability, and consumer preference evolution. Municipal solid waste management continues to face mounting pressure, with food waste representing a significant share of landfill volume and contributing disproportionately to methane emissions. This reality has elevated disposal units from convenience appliances to recognized components of broader waste diversion strategies.
Simultaneously, wastewater treatment infrastructure in many regions has advanced to the point where disposed food waste can be processed into renewable energy and nutrient-rich byproducts. This closed-loop potential strengthens the environmental case for disposer adoption and provides a regulatory and sustainability narrative that manufacturers, distributors, and commercial facility operators can leverage in their positioning. Government initiatives that promote sustainable waste management practices further reinforce procurement preferences for higher-rotation, higher-efficiency units capable of processing a broader range of organic waste with reduced clogging and maintenance overhead.
On the commercial and residential installation side, total project economics remain a critical decision factor. Professional replacement and installation workflows carry meaningful cost considerations, and end-user sensitivity to leak prevention, code compliance, and long-term reliability continues to influence brand selection and channel partnerships. These dynamics create an environment where product durability, service network strength, and installer education become differentiators as important as unit-level specification sheets.
For 2026 strategy teams, these drivers translate into several actionable imperatives: aligning product roadmaps with sustainability messaging that resonates with both regulators and end-users, evaluating pricing and installation-service bundling opportunities, and preparing for regulatory environments that may accelerate adoption in specific jurisdictions while constraining less efficient legacy technologies in others.
Competitive Landscape and Corporate Strategy Signals
The market features a diverse set of established appliance manufacturers, specialized disposal producers, and plumbing fixture brands that compete across residential and commercial segments. Competitive differentiation is increasingly rooted in technology integration, acoustic performance, connectivity and serviceability features, and the ability to embed disposal solutions within broader kitchen or facility equipment ecosystems.
Market concentration remains moderately fragmented, with leading players holding a combined share that leaves substantial room for regional specialists, niche innovators, and portfolio-integrated appliance brands to compete on specific value propositions. This structure encourages continuous feature evolution and creates a landscape where strategic partnerships, channel alignment, and brand positioning can be as impactful as volume production scale.
Several incumbents have demonstrated how targeted portfolio moves and product launches can recalibrate market expectations. InSinkErator, recognized as the world's largest manufacturer of food waste disposers, continues to emphasize multi-stage grinding architectures, sound-dampening engineering, and simplified connectivity features across its residential and commercial lines. Recent catalog and point-of-sale material releases have highlighted next-generation disposer designs alongside integrated hot water tap offerings, signaling a broader push toward kitchen experience enhancement rather than isolated appliance performance.
Whirlpool Corporation leverages its global production and distribution footprint by integrating food waste disposers into a wider kitchen appliance portfolio, enabling cross-selling opportunities and unified service narratives across installed bases. Anaheim Manufacturing Company operates through the Waste King brand, delivering a full line of residential and commercial disposers that emphasize durability and broad performance coverage. Moen Incorporated positions garbage disposals within its plumbing fixture ecosystem, aligning disposal offerings with faucet and sink configurations for residential kitchen projects. GE Appliances maintains continuous-feed disposal options within its home appliance lineup, drawing on brand recognition and install-base familiarity. Joneca Company, LLC focuses on high-quality residential and commercial disposers and adjacent kitchen appliance products, while Franke Management AG targets premium disposal solutions for European and global residential markets, underlining the importance of regional design expectations and finish integration.
On the commercial side, Salvajor specializes in commercial-grade garbage disposals and food waste systems, addressing high-throughput environments where reliability, service intervals, and compliance with commercial kitchen standards are decisive procurement factors.
These corporate profiles illustrate a market where competitive advantage is built through a combination of product engineering, channel strength, brand trust, and segmentation focus. For 2026 planning, the strategic question is not simply who holds share today, but which players are best positioned to capture demand shifts arising from regulatory momentum, installer preferences, and commercial facility upgrade cycles.
Beyond established players, the market is also being influenced by discrete operational events that signal where management attention is flowing. Recent catalog launches, updated point-of-sale materials, and product showcase initiatives indicate intentional efforts to reset buyer expectations around performance, aesthetics, and integrated kitchen solutions. These moves often precede broader pipeline changes, making them valuable leading indicators for competitive monitoring and benchmarking.
Garbage Disposer Market
Worldwide Kitchen Food Waste Disposal Machine Market
What the Full Research Study Delivers
This market study is structured to move beyond surface-level sizing and provide an operational intelligence framework that strategy, finance, and product teams can apply directly. The analysis integrates historical performance, forward forecasts, segmentation logic, competitive profiling, and industry context into a single decision-support architecture. The objective is to equip stakeholders with a clear line of sight from macro trends to segment-level implications, without relying on assumptions that rapidly age out of relevance.
The report unpacks the demand environment across residential and commercial use cases, examining how installation behavior, replacement cycles, end-user priorities, and commercial throughput requirements shape volume distribution. It evaluates the type-level composition of the market, highlighting how performance characteristics, material considerations, and application fit influence adoption patterns and price sensitivity. Regional analysis is presented with an emphasis on structural demand drivers, infrastructure readiness, and market maturity differentials, allowing planners to assess where growth is most durable and where execution risk is highest.
Competitive intelligence sections profile the major participants, mapping their product architectures, brand positioning, channel dynamics, and recent strategic actions. This enables benchmarking of feature sets, identification of whitespace opportunities, and assessment of how portfolio breadth or specialization affects competitive resilience. The study also incorporates regulatory and environmental context, including waste diversion statistics, methane emission dynamics, and the role of wastewater treatment capabilities in reinforcing the value proposition of modern disposers. Infrastructure and installation economics are addressed as practical planning inputs, ensuring that total cost-of-ownership considerations are reflected in market modeling rather than treated as afterthoughts.
Importantly, the research framework is designed to support multiple internal use cases. Corporate development teams can use it to evaluate partnership and acquisition targets. Product leaders can use it to prioritize feature investment and specification roadmaps. Sales and marketing organizations can use it to shape channel messaging and installer engagement programs. Finance and strategy functions can use it to stress-test revenue scenarios and align capacity planning with demand inflection points.
Implications for 2026 Strategic Decision-Making
As organizations finalize 2026 plans, the garbage disposer market presents a clear test of strategic discipline. Growth is forecast to continue at a steady pace, but the distribution of that growth across segments, regions, and application types will reward those who can translate market-level trends into targeted execution. The firms that outperform will be those that connect product performance, installer relationships, sustainability positioning, and commercial service reliability into a coherent value proposition.
Several strategic questions should guide internal planning. How does the organization intend to position against both portfolio-integrated appliance brands and specialized disposer manufacturers? Which performance attributes and installation-service factors most influence purchase decisions in the target segment, and how should messaging and channel incentives be structured around them? Where do regulatory and infrastructure trends create the strongest adoption pull, and how should go-to-market resources be weighted across regions with differing maturity levels? How should product engineering and warranty/service strategies evolve to reduce total cost-of-ownership concerns and strengthen long-term brand trust?
Addressing these questions requires market intelligence that is both credible and actionable. Macro-level sizing and growth expectations provide the strategic backdrop, but the real planning advantage comes from understanding the segmentation logic, competitive dynamics, and industry context that determine where share gains are achievable and where defensive positioning is necessary.
Accessing the Full Market Intelligence
This overview has outlined the strategic contours of the garbage disposer market and demonstrated how the full research study is designed to support 2026 decision-making across product, commercial, and corporate functions. The complete report provides the detailed segmentation analysis, competitor benchmarking, regional structural assessment, and scenario-ready forecasting that executives and planners need to move from broad trend awareness to precise strategic action.
Readers seeking the full dataset, segment-level breakdowns, company profiles, and forward-looking modeling can access the complete market research through our official publication channel. The comprehensive study is built to serve as a working intelligence asset throughout the planning cycle, enabling teams to validate assumptions, compare strategic options, and align execution with the most reliable view of market direction available.
For organizations preparing to invest, expand, reposition, or defend in the garbage disposer market, the difference between reactive planning and strategic advantage lies in the depth and reliability of the intelligence underpinning decisions. The full report delivers that foundation, and it is available now for teams ready to translate market insight into 2026 execution.
For detailed analysis of this topic, please visit the official page: Garbage Disposer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air & Water Pollution Control Market Hits $143.5M in 2025, Projected 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
The Air & Water Pollution Control Equipment Market: Navigating Growth, Regulation, and Consolidation in 2026
The global Air & Water Pollution Control Equipment Market stands at a critical inflection point as we move deeper into 2026. For industrial leaders, environmental executives, and capital allocators, the sector is no longer defined solely by compliance checklists or reactive remediation. It has evolved into a strategic imperative where operational resilience, regulatory anticipation, and technological differentiation converge. Our latest comprehensive research publication examines this shifting landscape, offering a structured, forward-looking intelligence framework designed specifically to inform capital planning, competitive positioning, and long-cycle investment decisions throughout 2026 and beyond.
Pre-Inflection Trajectory and Base Performance
The market has already transitioned from a phase of post-pandemic recovery into a sustained, structurally supported growth corridor. Spanning a meticulous historical review from 2020 through 2025, the analysis establishes a clear baseline of consistent expansion. Revenue progression across this period demonstrates steady compounding, anchored by tightening environmental mandates, industrial modernization cycles, and the steady replacement of legacy control systems. Against this backdrop, the forecast horizon extending to 2032 paints a trajectory of durable acceleration. The projected five-year compound annual growth rate of 5.5 percent signals a market that is broadening rather than merely inflating, driven by cross-sector demand and the gradual but irreversible shift toward higher-efficiency abatement technologies.
This sustained climb is not a transient reaction to isolated policy shocks or temporary capital reallocations. Instead, it reflects the maturation of a sector where pollution control has become deeply embedded in core engineering specifications, environmental health and safety governance, and plant-level lifecycle economics. The sheer scale of the projected expansion, measured in hundreds of millions of USD, underscores how both air and water control infrastructure have graduated from discretionary retrofit expenditures to baseline operational necessities across heavy industry.
A Study Built for Executive Decision-Making
The market study was engineered to function as an operational compass rather than a static data repository. At its core, the report delivers granular segmentation that isolates the structural drivers of demand across both air and water control disciplines. By examining equipment typologies, industrial applications, and regional deployment patterns, the analysis reveals where growth is organically emerging and where saturation or pricing pressure is beginning to reshape procurement strategies. Importantly, the segmentation insights expose the shifting balance between mature end-markets and high-velocity industrial verticals, providing context on how capital flows are redistributing across competing applications.
Beyond pure segmentation, the publication maps the competitive architecture that defines today’s marketplace. The industry operates with a deliberately distributed player base, where collective top-tier coverage accounts for less than one-third of aggregate market share. This moderate concentration level indicates room for specialized innovators, regional specialists, and technology-led entrants to capture meaningful share without navigating an impenetrable oligopoly. The research dissects this competitive topology by evaluating how incumbent firms are recalibrating their portfolios, where adjacent technology plays are creating cross-market opportunities, and which operational models are proving most resilient as procurement cycles lengthen and engineering customization demands increase.
For procurement directors and engineering managers, the report provides actionable intelligence on specification migration trends, retrofit economics, and lifecycle cost dynamics. For investors and corporate strategy teams, it maps consolidation pathways, partnership vectors, and geographic diversification considerations that are actively reshaping deal flow and M&A rationale across the environmental equipment ecosystem.
Market Dynamics and the Regulatory-Industrial Feedback Loop
The contemporary demand environment is being propelled by a reinforcing cycle of regulatory progress and industrial modernization. On the compliance axis, sustained reductions in criteria air pollutants and precursor emissions over the past decades have not eliminated the need for advanced control systems; rather, they have shifted the technical benchmark upward. Smaller particulate fractions, complex volatile organic compound streams, and stricter water effluent parameters now require higher-precision filtration, more selective adsorption, and tightly integrated monitoring architecture. The consequence is a market where incremental upgrades and full-system replacements coexist, creating a steady baseline of demand even in mature stationary-source environments.
Simultaneously, macroeconomic and supply-side variables are injecting a fresh layer of complexity into procurement timelines and engineering economics. Recent sharp upward movements in key polymer and resin input costs, driven by shipping disruptions that have perturbed global trade flows, are directly affecting the manufacturing economics of polymer-based components used across pollution control assemblies. For OEMs and system integrators, this translates into nuanced margin management, strategic inventory buffering, and accelerated evaluation of alternative material streams. The research captures how these raw material dynamics are filtering through to final equipment pricing, lead-time expectations, and vendor negotiation leverage during 2026 procurement cycles.
These operational pressures are unfolding alongside continued consolidation and strategic realignment at the corporate level. Industry participants are actively rewiring their business portfolios to concentrate resources on high-margin control technologies and high-growth geographic clusters. The resulting realignment is creating a more differentiated competitive field, where firms that can combine application-specific engineering depth with robust service and monitoring capabilities are pulling ahead in bid evaluations and long-term service contracts.
Air & Water Pollution Control Equipment Market
Competitive Architecture and Strategic Positioning
The competitive landscape of the air and water pollution control sector is characterized by a blend of established process-engineering houses, regional specialists, and technology-focused innovators. Each major participant brings a distinct operational footprint and a targeted capability set that aligns with specific industrial emissions profiles and water treatment requirements.
CECO Environmental, headquartered in Addison, Texas, continues to anchor its offering in advanced filtration and emissions control systems spanning scrubbers, cyclones, biofiltration, and thermal oxidizers. Its portfolio is particularly oriented toward power, refinery, and broader industrial air pollution control deployments, where integrated system design and emissions reduction reliability drive end-user selection. Ducon Environmental Systems, based in Farmingdale, New York, complements this landscape with a focused toolkit of advanced air pollution control systems including wet electrostatic precipitators, baghouses, cyclones, wet scrubbers, and activated carbon platforms, all engineered for demanding industrial emissions control scenarios.
Across the Atlantic, Airnord in Copenhagen has positioned itself in the high-tech segment of air pollution control, emphasizing electrostatic precipitators and comprehensive emissions management systems that cater to facilities requiring precision particulate and aerosol capture. In India, Thermax from Pune delivers industrial air pollution control systems designed for both particulate and gaseous pollutant abatement, reflecting the intense demand dynamics of rapidly industrializing environments where cost-performance optimization remains paramount.
KC Cottrell, operating from Seoul, South Korea, rounds out a significant Asia-Pacific engineering presence with air quality control systems that include electrostatic precipitators, fabric filters, flue gas desulfurization, and denox solutions tailored for power generation and industrial applications. Its technology breadth underscores the growing integration of multi-pollutant control strategies within single plant environments.
Water-side capability is equally critical to the broader market narrative. Pentair, headquartered in London, contributes advanced water and wastewater treatment solutions that encompass sophisticated filtration and pollution control equipment, addressing both municipal-grade treatment expectations and industrial discharge compliance. HUBER Group, based in Berching, Germany, reinforces this spectrum with high-quality machines, plants, and equipment designed for municipal and industrial water, wastewater, and sludge treatment, offering a portfolio that bridges mechanical separation, biological processing, and sludge handling.
Recent corporate movements illustrate how quickly the competitive map is being redrawn. In June 2025, FLSmidth announced an agreement to divest its Air Pollution Control business to Rubicon Partners, with the business continuing as Airnord while retaining its existing technology base and customer relationships. That transition highlights how asset-level portfolio pruning can sharpen a company’s strategic focus without disrupting installed-base continuity. More recently, in mid-2026, CADAIR Environmental Technology showcased advanced industrial air pollution control solutions for volatile organic compounds and emission reduction at IE Expo China, signaling continued product-level innovation and regional engagement. Similarly, Anguil’s return to the 48th annual SESHA Symposium in Tempe, Arizona, in April 2026 for air pollution control discussions reflects ongoing emphasis on specialty industrial safety, emissions management, and direct operator-facing technology engagement.
Together, these profiles and developments illustrate an ecosystem where specialization, geographic reach, and post-acquisition brand continuity are becoming decisive factors in competitive positioning. Rather than competing purely on equipment commoditization, leading players are differentiating through application-specific engineering, lifecycle service models, and the ability to navigate complex multi-stack, multi-stream control challenges.
How to Use This Research in 2026 Strategy Planning
The market study is structured to support three distinct decision-making layers. First, for corporate strategy and corporate development teams, it provides a framework to evaluate where inorganic growth, partnership, or geographic expansion carries the highest probability of sustainable returns. The analysis clarifies the segments where demand is expanding fastest and where competitive intensity may compress future profitability, helping leadership avoid overinvestment in already crowded applications while identifying overlooked value pools.
Second, for engineering, procurement, and operations leaders, the research offers a structured view of technology migration patterns, retrofit versus greenfield decision drivers, and material cost sensitivities that influence total cost of ownership. By understanding where specification requirements are shifting and how supply-side cost pressures are propagating through equipment classes, teams can better sequence capital expenditures, negotiate supplier agreements, and de-risk long-lead procurement decisions.
Third, for investors and market entrants, the report maps the competitive fragmentation, concentration dynamics, and recent realignment events that shape entry feasibility and partnership opportunities. The moderate market concentration observed in the sector suggests that scale alone is not the sole gatekeeper to market success; differentiated technology, service integration, and regional execution capability remain highly valuable. This creates a landscape where disciplined niche strategies and targeted technology plays can achieve meaningful market penetration without requiring broad-spectrum scale from day one.
The research also incorporates operational real-world variables, including recent raw material cost shifts affecting polymer-based component sourcing and the continuing regulatory momentum that sustains demand across stationary sources. By integrating these external pressures directly into segment-level analysis, the report enables decision-makers to stress-test strategies against both regulatory continuity and supply-chain volatility rather than relying on idealized planning scenarios.
Water Treatment Equipment Market
Accessing the Full Intelligence Package
This article has provided a strategic overview of the forces shaping the Air & Water Pollution Control Equipment Market as organizations navigate 2026 planning cycles. Yet the full value of the research lies in its detailed segmentation architecture, end-market deployment logic, competitive profiling, and forward forecasts that move well beyond high-level narrative. To capture the complete analytical depth required for precise capital allocation, product portfolio decisions, and competitive benchmarking, we invite you to explore the full report at its source webpage. There, the complete data sets, segmentation breakdowns, and company-level profiles are available to support the more granular work of strategy formulation, procurement sequencing, and investment prioritization.
In a market where regulatory momentum, material cost dynamics, and corporate realignment are simultaneously reshaping competitive advantage, timely and structured intelligence is not simply useful; it is foundational to making resilient decisions. We look forward to supporting your strategic work with the full depth of this analysis.
For detailed analysis of this topic, please visit the official page: Air & Water Pollution Control Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Last Mile Delivery Market to Hit $353.57M by 2032 at 9.8% CAGR
By PW Consulting, 2026-09-16
Last Mile Delivery Market Outlook 2026: Navigating Growth, Complexity and Strategic Opportunity
The last mile delivery sector stands at a decisive inflection point. As urban commerce accelerates and consumer expectations converge around speed, transparency and reliability, the operational layer that moves goods from local depots to end recipients is no longer a cost center to be minimized. It is a competitive battleground that shapes brand loyalty, margin structures and geographic expansion. Our latest market research on the Last Mile Delivery Market translates this complexity into a structured, decision-ready intelligence framework designed explicitly for leaders planning their 2026 operating and investment strategies.
This research is built for executives who need to move beyond headline market narratives. It maps the trajectory of the sector through a rigorous historical-to-forecast lens, anchors growth assumptions in verifiable market sizing, and then unpacks the operational, competitive and regulatory forces that will separate resilient operators from those forced into reactive positioning. The objective is straightforward: provide a precise enough view of where the market is heading to inform capital allocation, partnership evaluation, technology roadmapping and regional prioritization, while deliberately leaving the most granular breakdowns for the full report.
Market Trajectory and the Strategic Context for 2026
Over the past five years, the last mile delivery market has demonstrated a consistent expansion trajectory thatoutpaces many adjacent logistics segments. Historical market sizing from 2020 through 2025 reflects a compound growth pattern shaped by e-commerce penetration, retail network reconfiguration and the normalization of same-day and next-day fulfillment expectations. From a base of approximately 115.2 million USD in 2020, the market expanded steadily year over year, reaching an estimated 183.76 million USD by 2025. This historical run-rate sets the foundation for the forward-looking period, and the forecast horizon through 2032 signals that the sector is not merely sustaining momentum but accelerating it.
The projected compound annual growth rate of 9.8 percent across the forecast window positions last mile delivery as one of the more structurally attractive segments within the broader logistics and supply chain ecosystem. Growth is not uniform across time or geography, and the report treats that heterogeneity as a strategic variable rather than background noise. By 2026, market sizing moves to an estimated 204.78 million USD, and forward projections extend upward through the early 2030s, with the trajectory reflecting the combined effects of volume expansion, vehicle and technology mix evolution, and service model diversification. The strategic implication for 2026 planning is clear: organizations that treat last mile delivery as a fixed-cost operational function will face a widening gap relative to competitors who design their networks around scalable, data-driven cost-to-serve models.
For decision-makers, the most valuable lens is not the size of the market alone, but the structure of participation within it. The report examines market concentration patterns that illustrate how value is distributed across incumbents, technology-forward platforms and specialized regional operators. This concentration context matters because it informs realistic expectations around vendor leverage, partnership competition, pricing power and the likelihood of consolidation. Rather than presenting a simple leaderboard, the analysis situates concentration within the operational realities of routing optimization, workforce management, regulatory exposure and customer communication expectations that now define competitive parity.
What the Research Delivers: An Executable Intelligence Framework
This market research is structured as a practical instrument for strategy, operations and investing teams, not merely a descriptive overview. The report combines market sizing, forecast modeling and segmentation analysis with a detailed mapping of competitive offerings, recent corporate activity and the operational forces reshaping cost and service economics. The intent is to provide a common factual foundation that can support scenario planning, vendor evaluation, market entry analysis and operational redesign.
The segmentation architecture explores how the market decomposes across vehicle types, service approaches, delivery models and end-use applications. These dimensions are analyzed to surface where operating economics diverge, where technology adoption is driving measurable efficiency gains, and where structural headwinds or regulatory pressure may alter the attractiveness of specific pathways. Regional splits are examined to reflect differences in urban density, infrastructure readiness, labor market dynamics and consumer purchasing behavior. The analysis is deliberately framed to show how each segment influences cost structures and service feasibility, so that leaders can assess where their own operating model is most exposed or most advantaged.
Beyond segmentation, the report delivers a detailed competitive landscape that profiles leading platforms and logistics software providers. These profiles are built around real operating capabilities rather than marketing positioning, covering route optimization logic, real-time visibility, dispatch and courier network management, exception handling, customer communication and integration patterns. The research also tracks recent corporate developments that signal how capital and partnerships are being deployed to reshape competitive positioning. These developments include major acquisition activity, cross-market expansion moves, same-day shipping partnerships and capacity-strengthening transactions. Read together, they reveal where incumbents are reinforcing their networks, where technology platforms are pursuing scale, and where consolidation is likely to alter procurement and partnership options.
The research also integrates the operating conditions that determine whether growth translates into profitable execution. Labor economics remain a central pressure point, with workforce costs representing a substantial share of total last mile expenses and express delivery commanding premium wage structures. At the same time, regulatory attention is intensifying around urban delivery facilities, truck emissions, subcontracted labor models and local traffic management. Cities are expected to impose stronger restrictions on delivery traffic over the coming years, creating a structural tension between rising parcel volumes and sustainability and access constraints. Energy costs, labor availability and the disproportionate operating cost burden associated with the final delivery stage all reinforce a central point: volume growth alone does not guarantee margin expansion. The report uses these dynamics to help leaders identify where operational redesign, automation, route density improvement and network orchestration can materially shift cost-to-serve outcomes.
Importantly, the report maintains a disciplined boundary between public-facing industry context and proprietary analytical depth. High-level market sizing, concentration indicators and segment architecture provide a strong directional foundation, while the finer breakdowns in regional share, application-level value, vehicle-type splits and company-level benchmarking are reserved for the full study. This design allows executive readers to immediately grasp the strategic shape of the market while preserving the report's differentiated data as a reason to engage with the complete intelligence package.
Strategic Decisions the Report Is Built to Inform
The research is organized around several high-stakes decisions that leaders are actively facing for 2026 and adjacent planning cycles. First, it supports market prioritization logic by clarifying how growth patterns, concentration and operating conditions differ across geographies and usage contexts. For organizations evaluating new regional entry, expansion sequencing or capacity investment, the report provides a framework for weighing demand momentum against infrastructure readiness, labor dynamics and regulatory friction.
Second, the analysis is built to support technology and vendor strategy. As last mile operations become more dependent on routing intelligence, real-time visibility and customer-facing communication, the choice of platform or orchestration layer increasingly determines service consistency and operational flexibility. The competitive profiles and operating capability comparisons help teams assess which solution characteristics matter most for their delivery model, fleet composition, courier network structure and exception-management requirements.
Third, the research informs partnership and procurement planning in a period of active consolidation. Recent acquisition activity and partnership announcements in the broader delivery ecosystem signal that the vendor landscape is changing quickly. For operators negotiating routing software, courier networks, fulfillment partnerships or capacity agreements, the report provides context on where capabilities are being combined, where scale is being accumulated, and where competitive tension may create better negotiating positions or, conversely, reduce alternative sourcing options.
Last Mile Delivery Market
Fourth, the study is designed to support cost and service trade-off analysis. Because labor intensity, traffic restrictions, energy expenses and density variability all influence profitability, leaders need a structured way to evaluate where service-level commitments are economically sustainable and where operational redesign is necessary. The report frames these trade-offs without over-simplifying them, allowing executives to identify the levers most relevant to their own network design, vehicle mix and service promises.
Same-day Delivery Market
How to Use This Research for 2026 Planning
The strongest value of this research emerges when it is used as a shared reference point across strategy, operations, procurement and technology teams. Rather than treating market growth as a single metric, leaders can use the report to align on the underlying drivers that make growth achievable or risky in specific contexts. That includes differentiating between demand-led expansion and capacity-led expansion, between technology-enabled efficiency and labor-dependent service models, and between regions where regulatory and infrastructure conditions support rapid scaling versus those where access and cost pressures require more cautious sequencing.
For capital planning, the report supports more disciplined scenario construction by linking historical growth, forecast momentum and concentration patterns to realistic assumptions about vendor selection, partnership availability and operating cost behavior. For operational planning, it helps identify where route optimization, visibility, customer communication and exception management are likely to remain differentiators rather than table stakes. For corporate development and partnership teams, the recent activity tracked in the research offers a practical lens on where consolidation and capability accumulation are reshaping the competitive map.
The analysis also encourages leaders to think in terms of resilience rather than optimization alone. In a market where parcel volumes continue to rise while regulatory, labor and access constraints intensify, the most durable operating models are those that can adapt vehicle mix, dispatch logic, customer communication and network density without sacrificing service reliability. The research provides the factual scaffolding needed to evaluate where that adaptability is already present and where it must be built.
Accessing the Full Intelligence
The overview presented here establishes the strategic shape of the last mile delivery market, surfaces the core operating and competitive dynamics shaping 2026 decisions, and frames the decisions the full research is designed to support. What it does not attempt is to extract the complete segmentation detail, company-level benchmarking, regional value breakdowns or proprietary analytical conclusions that give the study its decision-grade specificity. Those elements are preserved in the full report so that executives, analysts and operating leaders can work from a precise, internally consistent dataset rather than a generalized summary.
For teams that need to allocate budget, select vendors, prioritize markets, assess partnership options or redesign cost-to-serve logic in the current environment, the full research offers the depth required to move from directional awareness to concrete action. The objective of this introduction is to give you enough substantive insight to recognize the analytical rigor behind the study, while maintaining the core data and differentiated findings as a reason to access the complete market research directly.
If your 2026 planning depends on a clear, evidence-based view of where last mile delivery is heading and how leading operators are repositioning around it, the full report provides the structured intelligence necessary to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Last Mile Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com